MedTech Retirement Benefits 2026: 401(k) vs. Pension Analysis
Anúncios
MedTech Retirement Benefits 2026: A Data-Driven Analysis of 401(k) and Pension Plans
The MedTech industry, a dynamic and rapidly evolving sector, continues to attract top talent with its promise of innovation and impact. As professionals dedicate their careers to advancing healthcare technology, the allure of robust retirement benefits becomes a critical factor in career decisions and long-term financial planning. For 2026, understanding the nuances of MedTech retirement benefits, particularly the differences between 401(k) and traditional pension plans, is more vital than ever. This comprehensive analysis will delve into the data, trends, and strategic considerations for MedTech employees navigating their financial future.
Anúncios
Anúncios
Retirement planning is not a one-size-fits-all endeavor, especially within an industry as specialized as MedTech. The choices made today regarding retirement contributions and plan types can significantly impact financial security decades down the line. We will explore the characteristics, advantages, and disadvantages of both 401(k) and pension plans within the MedTech context, offering a data-driven perspective to help you make informed decisions about your MedTech retirement benefits.
The Evolving Landscape of MedTech Retirement Benefits
The landscape of retirement benefits has shifted dramatically over the past few decades. While traditional pension plans once dominated, the 401(k) has emerged as the prevalent retirement vehicle in many industries, including MedTech. This evolution reflects broader economic trends, changing corporate philosophies, and a greater emphasis on individual responsibility for retirement savings. However, some MedTech companies, particularly older, more established firms or those with a strong union presence, may still offer robust pension plans, or a hybrid approach.
For MedTech professionals, the choice or availability of these plans directly impacts their financial trajectory. A deep understanding of each plan’s structure, contribution mechanisms, vesting schedules, and payout options is paramount. As we approach 2026, economic forecasts, inflation rates, and market volatility will continue to influence the performance and perceived value of these retirement vehicles. Therefore, staying informed about the latest trends in MedTech retirement benefits is not just advisable, but essential.
Understanding 401(k) Plans in MedTech
The 401(k) plan is a defined contribution plan, meaning that contributions are made by both the employee and, often, the employer into an individual account. The retirement benefit at retirement depends on the total contributions made and the investment performance of the chosen funds. For MedTech employees, 401(k) plans offer several key features:
- Employee Contributions: Employees can contribute a portion of their pre-tax salary, reducing their current taxable income. There are annual contribution limits set by the IRS, which tend to increase over time.
- Employer Matching: Many MedTech companies offer employer matching contributions, which can significantly boost an employee’s savings. This is essentially free money and should be maximized whenever possible. A common match might be 50 cents on the dollar up to 6% of salary.
- Investment Options: Participants typically have a range of investment options, including mutual funds, index funds, and sometimes company stock. This allows for diversification and customization based on individual risk tolerance and financial goals.
- Portability: One of the significant advantages of a 401(k) is its portability. If a MedTech professional changes jobs, they can roll over their 401(k) into an IRA or their new employer’s 401(k) plan, maintaining control over their retirement savings.
- Vesting Schedules: Employer contributions often come with a vesting schedule, meaning an employee must work for the company for a certain period before they fully own the employer’s contributions. Common vesting schedules include cliff vesting (100% after a certain number of years) or graded vesting (a percentage vests each year).
- Tax Advantages: Contributions grow tax-deferred, meaning taxes are paid only upon withdrawal in retirement. Roth 401(k) options, where contributions are made with after-tax dollars but withdrawals in retirement are tax-free, are also becoming more common.
Data from recent years suggests that the average 401(k) balance for individuals in the healthcare and technology sectors (which MedTech straddles) tends to be higher than the national average, often due to competitive employer contributions and higher average salaries. However, individual balances vary widely based on contribution rates, investment choices, and years of service. For MedTech professionals, leveraging the full potential of their 401(k) through consistent contributions and strategic investment is crucial for building substantial MedTech retirement benefits.
The Enduring Appeal of Pension Plans in MedTech
Pension plans, specifically defined benefit plans, promise a specified monthly benefit at retirement, typically based on a formula involving salary, years of service, and age. While less common in the private sector today, some established MedTech firms or those with a history of strong employee benefits may still offer these plans. Key characteristics include:
- Guaranteed Income: The most attractive feature of a pension is the promise of a predictable, lifelong income stream in retirement, regardless of market performance. This provides a strong sense of financial security.
- Employer Funded: Pensions are almost entirely funded by the employer, reducing the direct financial burden on the employee during their working years.
- No Investment Decisions: Employees do not need to make investment decisions; the employer bears the investment risk and manages the pension fund.
- Complex Vesting: Pension plans often have longer vesting periods than 401(k)s, sometimes requiring 5 to 10 years of service to become fully vested.
- Lack of Portability: Pensions are generally not portable. If an employee leaves before retirement, they may receive a reduced benefit or a lump-sum payout, but the guaranteed income stream is typically tied to remaining with that specific employer until retirement.
While the prevalence of traditional defined benefit pension plans has declined, their value for long-tenured employees in MedTech cannot be overstated. The security of a guaranteed income stream can be a powerful incentive for retention and provides a strong foundation for MedTech retirement benefits. However, the trend clearly favors defined contribution plans, making it essential for MedTech professionals to understand if a pension is even an option for them.
Comparing 401(k) and Pension Plans: A Data-Driven Approach for 2026 MedTech Retirement Benefits
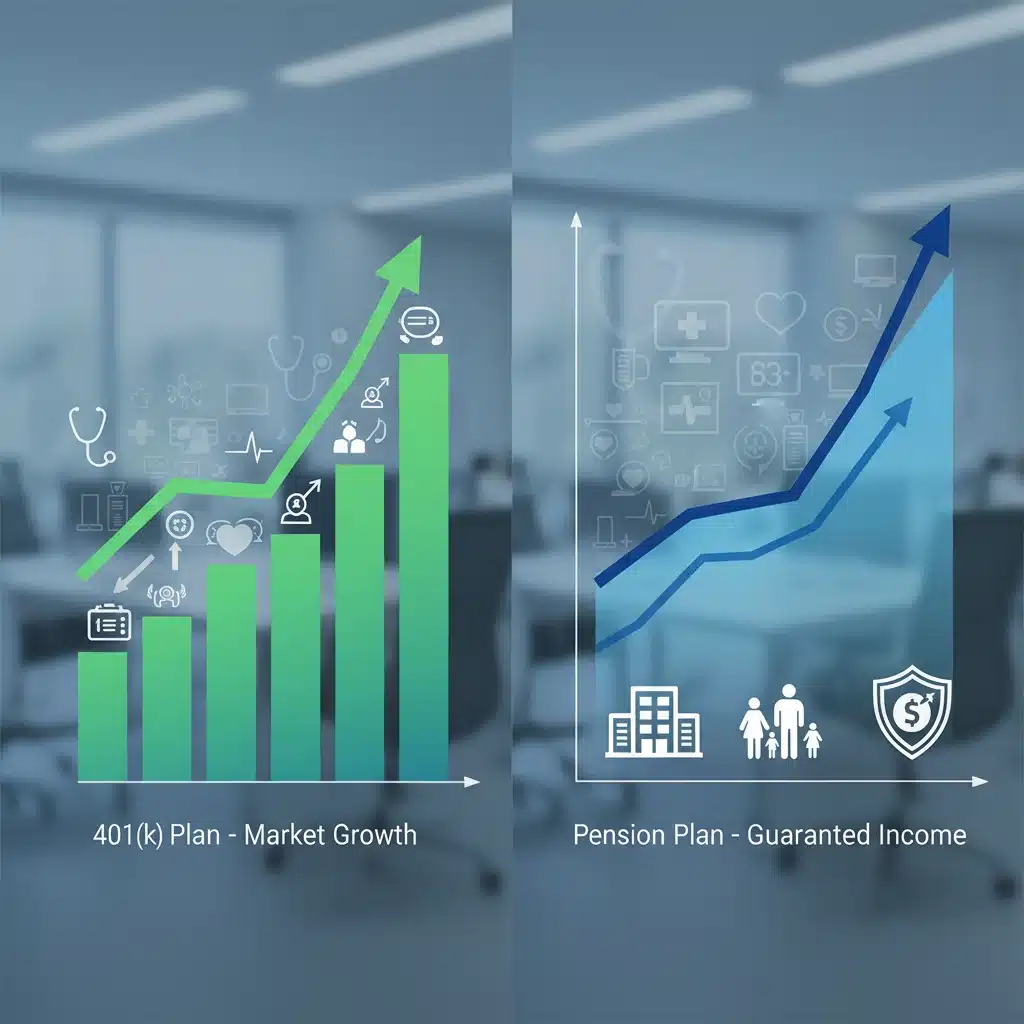
To make an informed decision about your MedTech retirement benefits, it’s crucial to compare 401(k) and pension plans across several critical dimensions. The optimal choice often depends on individual circumstances, career goals, and risk tolerance.
Risk and Returns
- 401(k): The employee bears the investment risk. Returns are directly tied to market performance and investment choices. While this offers potential for higher growth, it also carries the risk of market downturns. Diversification and periodic rebalancing are key strategies to mitigate risk. Historically, well-managed 401(k) portfolios have offered strong long-term returns, but past performance is not indicative of future results.
- Pension: The employer bears the investment risk. The employee receives a defined benefit regardless of the pension fund’s investment performance. This provides greater certainty and stability, making it ideal for those who prefer less investment risk. However, the guaranteed benefit is typically lower than the potential growth of a high-performing 401(k).
Flexibility and Control
- 401(k): Offers significant flexibility and control. Employees choose their contribution amounts (within IRS limits), select investment options, and can roll over funds if they change jobs. This autonomy allows individuals to tailor their retirement strategy to their evolving financial situation and risk appetite.
- Pension: Provides very little flexibility or control for the employee. The benefit formula is predetermined, and investment decisions are made by the employer. Portability is limited, which can be a disadvantage for MedTech professionals who anticipate changing companies multiple times throughout their career.
Contribution and Funding
- 401(k): Funded by both employee and employer contributions. Employee contributions are elective and can be adjusted. Employer contributions, especially matching, are a significant boost to savings.
- Pension: Primarily funded by the employer. Employees typically do not contribute directly, though some plans may require minor employee contributions. This can be seen as an additional benefit for employees, as their take-home pay is not reduced for retirement savings.
Payout Options
- 401(k): At retirement, funds can be withdrawn as a lump sum, rolled into an IRA for continued investment, or converted into an annuity. This flexibility allows retirees to manage their income stream as they see fit.
- Pension: Typically offers a monthly annuity payment for life, often with options for a survivor benefit for a spouse. Some plans may offer a lump-sum payout option, but this usually means forfeiting the guaranteed lifetime income.
Impact of Career Changes in MedTech
The MedTech industry is characterized by innovation, mergers, acquisitions, and a dynamic job market. This often means professionals change roles and companies more frequently than in traditional industries. This mobility has a significant impact on MedTech retirement benefits:
- 401(k) Advantage: The portability of 401(k) plans makes them highly suitable for mobile MedTech professionals. Funds can move with the employee, ensuring continuous growth and consolidation of retirement savings.
- Pension Disadvantage: Changing jobs frequently can severely diminish the value of a pension. If an employee leaves before being fully vested, they may lose all employer contributions. Even if vested, the benefit earned for a shorter tenure will be significantly less than for a full career with one employer.
Strategic Considerations for MedTech Professionals in 2026
As you plan for your financial future in the MedTech sector, consider these strategic points:
Maximize Employer Contributions
Regardless of whether your company offers a 401(k) or a pension, always understand and maximize employer contributions. For 401(k)s, this means contributing at least enough to get the full employer match. For pensions, it means understanding vesting schedules and the impact of tenure on your benefit.
Diversify Your Retirement Savings
Even if you have a strong 401(k) or pension, consider diversifying your retirement savings with other vehicles like IRAs (Traditional or Roth), Health Savings Accounts (HSAs) if eligible, or taxable brokerage accounts. This diversification can provide additional flexibility and tax advantages for your MedTech retirement benefits.
Understand Vesting Schedules
Vesting schedules are critical. For a 401(k), ensure you understand when employer contributions become fully yours. For a pension, know how many years you need to serve to be eligible for a benefit and when that benefit becomes fully vested. This knowledge is crucial when considering career changes within MedTech.
Factor in Inflation and Longevity
When evaluating the value of future retirement income, particularly from pensions, consider the impact of inflation. A fixed pension payment might lose purchasing power over time. For 401(k)s, choose investments that aim to outpace inflation. Also, with increasing life expectancies, ensure your retirement plan can sustain you for a potentially longer retirement period.
Seek Professional Financial Advice
The complexities of MedTech retirement benefits, combined with personal financial situations, often warrant professional guidance. A financial advisor specializing in retirement planning can help you analyze your specific plans, project future income, and develop a comprehensive strategy tailored to your goals. They can also help you understand the tax implications of different withdrawal strategies.
The Hybrid Approach: A Growing Trend in MedTech
Some MedTech companies are adopting hybrid retirement plans that combine elements of both defined contribution and defined benefit plans. These might include a cash balance plan, which looks like a defined benefit plan but has an individual account balance that grows at a specified rate, or a company that offers a robust 401(k) with a smaller, supplemental pension component. These hybrid plans aim to offer a balance of security and flexibility, catering to a diverse workforce and enhancing overall MedTech retirement benefits packages.
For employees in companies offering such hybrids, it’s essential to understand how these components interact. Often, the cash balance plan provides a predictable growth rate and a lump-sum option, while the 401(k) offers market-driven growth and investment control. This blended approach can provide a strong foundation for retirement, mitigating some of the risks associated with a single plan type.
Regulatory Changes and Their Impact on 2026 MedTech Retirement Benefits
Retirement plans are subject to federal regulations, and changes to these laws can impact MedTech retirement benefits. Legislation such as the SECURE Act and SECURE Act 2.0 has introduced significant changes, including:
- Increased Age for RMDs: The age for required minimum distributions (RMDs) from retirement accounts has been pushed back, allowing savings to grow tax-deferred for longer.
- Expanded Catch-Up Contributions: New provisions allow for larger catch-up contributions for older workers, providing more opportunities to boost savings closer to retirement.
- Emergency Savings Accounts: Some employers may now offer emergency savings accounts linked to retirement plans, providing a liquid savings option without impacting long-term retirement goals.
- Student Loan Matching: Future regulations might allow employers to match employee student loan payments with 401(k) contributions, a significant benefit for younger MedTech professionals burdened with educational debt.
Staying abreast of these regulatory changes is crucial for optimizing your MedTech retirement benefits. Employers and employees alike should consult with benefits administrators and financial advisors to understand how these laws affect their specific plans and strategies for 2026 and beyond.
Case Studies: Real-World MedTech Retirement Benefits Scenarios
To illustrate the practical implications of 401(k) versus pension plans, consider these hypothetical MedTech professional scenarios:
Scenario A: The Mobile Innovator (401(k) Focused)
Sarah, a 35-year-old R&D engineer, has worked for three different MedTech startups in her 10-year career. Each company offered a strong 401(k) with a 5% employer match. Sarah consistently contributed 10% of her salary, always maximizing the employer match. With each job change, she rolled her previous 401(k) into an IRA, consolidating her investments. By 2026, her aggressive investment strategy and consistent contributions have resulted in a substantial retirement nest egg, giving her the flexibility to pursue new opportunities without worrying about losing retirement benefits.
Scenario B: The Long-Tenured Specialist (Pension Focused)
David, a 55-year-old senior manufacturing manager, has spent 30 years at a well-established MedTech corporation that still offers a defined benefit pension plan, alongside a 401(k). David is fully vested in his pension, which promises a substantial monthly income based on his highest average salary and years of service. While he also contributed to his 401(k), the guaranteed income from his pension provides a foundational layer of security, allowing him to take a more conservative approach with his 401(k) investments as he approaches retirement in 2026. His loyalty to one company has been financially rewarded through his MedTech retirement benefits.
Scenario C: The Hybrid Beneficiary
Maria, a 45-year-old product development lead, works for a MedTech company that offers both a 401(k) with a 4% match and a cash balance pension plan. Maria contributes consistently to her 401(k), taking advantage of the match, and her cash balance plan has been steadily growing with a guaranteed interest credit. This combination provides her with both market-driven growth potential and a predictable, employer-funded component for her MedTech retirement benefits, offering a balanced approach to her financial future.
Conclusion: Charting Your Course for MedTech Retirement Benefits in 2026
The world of MedTech retirement benefits in 2026 is complex, offering a spectrum of options from employee-driven 401(k)s to employer-guaranteed pensions, and increasingly, hybrid models. For MedTech professionals, a proactive and informed approach to retirement planning is paramount. Understanding the specific features of your company’s offerings, maximizing employer contributions, and diversifying your savings are all critical steps.
Whether you prioritize flexibility and growth potential with a 401(k), or stability and guaranteed income with a pension, the key is to align your retirement strategy with your career trajectory, risk tolerance, and long-term financial goals. As the MedTech industry continues its rapid advancement, ensuring your MedTech retirement benefits are robust and well-managed will provide the security and peace of mind necessary for a fulfilling post-career life. Engage with your HR department, review your plan documents thoroughly, and consider consulting with a financial advisor to build the strongest possible foundation for your retirement.
Author